Who you are talking to
Zach von der Linden
Based in San Clemente. Works with homeowners in California, Utah, Oregon and Arizona.
I'm Zach von der Linden, NMLS 1652805, a mortgage broker and Branch Manager at West Capital Lending. I'm based in San Clemente, my branch office is in Irvine, and I put financing together for borrowers in California, Utah, Oregon and Arizona.
No credit pull happens from a text or a call. Texts and calls go to Zach's cell.
My NMLS: 1652805 · Over 10 years and counting in mortgages · 5.0 across 66 reviews on Experience.com (read on 2026-09-24)
You don't get handed off. I run a solo broker practice, so the person who answers your first question is the person who structures your loan. I put the financing together, and if no program fits, I'll say so.

 Branch Manager, West Capital Lending
The longer story
I moved to San Clemente when I was 5 and grew up here. The San Clemente page says what is different about financing a home here. Based in San Clemente. Branch office in Irvine.
I'm a mortgage broker with West Capital Lending, based in San Clemente with a branch office in Irvine. My own NMLS number is 1652805; West Capital Lending's company NMLS is 1566096. Both are listed under Licensing and identity below, each labeled with whose it is. Because I run a solo broker practice, the person who answers your first question is the person who structures the loan and the person you can call when something is confusing.
As a broker, I arrange loans with lenders and put the financing together; a lender makes the loan. I work with more than one wholesale lender and program, including home equity lines and conventional, government, bank statement and investment-property options, rather than selling one lender's product. The point of that is simple: you hear about the option that fits, or you hear that none of them do and you should wait. Which products are available depends on the home and the state.
About Zach
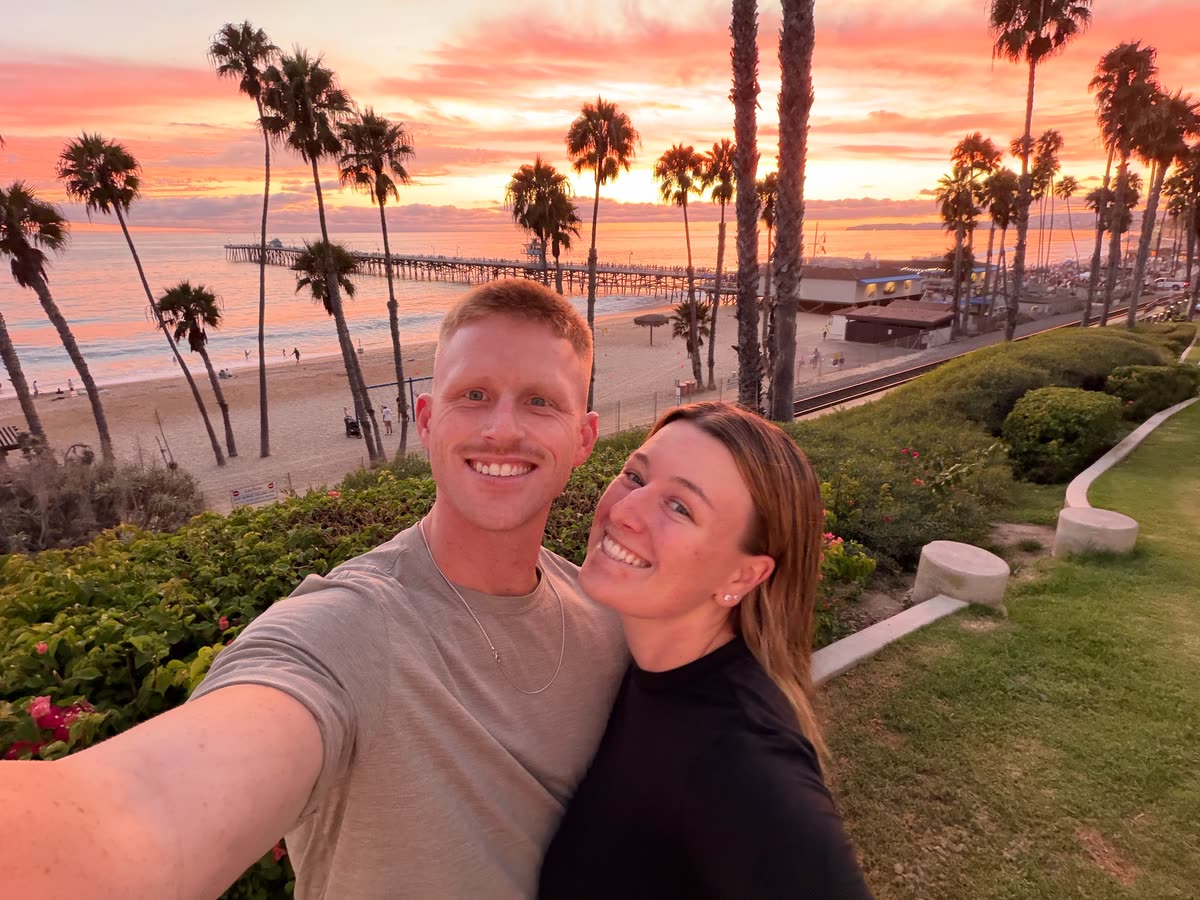
A note from Zach

Quick note, in Zach’s words
I really love what I do, and I love getting to know each of my clients and what you are trying to accomplish. I have always run my business by asking one question: how would I do this if I were in your shoes, or if you were my own family?
What makes that work is being a broker. I am not tied to one lender, so the whole point becomes finding the loan that actually fits you. If the first place is not right for you, we go to the place that is.
I take real pride in making sure everyone has a good experience and knows what is going on at every step. And I am here after closing too, in the months and years to come. You will always have my direct line, and we can always pick up where we left off. The goal is a connection, and an ally you can come back to. That is the benefit, and that is the point.
A few facts, so you know who you are talking to: over 10 years and counting in mortgages, first at banks, then at a direct lender as an employee, now as an independent broker who is not paid differently based on the type of loan product we put in front of you. That is what has built a business of repeat clients and referrals, and I look forward to adding you to it.
How he approaches a file
The first conversation is about what the money is for, when you need it, and what you already owe. Not documents, not a credit pull. A rough picture is enough to know whether a loan makes sense and which kind.
From there the process is the same one every page on this site follows: gross loan, fees off the top, what gets paid at closing, cash in hand, and the payment before and after. If a loan does not improve your situation, the answer is no, said plainly.
- Easy to reach and clear about the process, according to his clients’ reviews.
- Zach sizes the loan to the net you need, not the gross that looks impressive.
- Every page says which option fits and when another route fits better.
Broker or lender? What I can and cannot do
The questions people ask before they text, answered in my own words. If your mortgage was turned down, my bank denied my mortgage; what can I do now? covers what a second review looks at, and the hard-to-qualify hub lists the income situations I review.
Are you the lender for the loans you discuss?
No. I'm Zach von der Linden, NMLS 1652805, a mortgage broker and Branch Manager with West Capital Lending (company NMLS 1566096). I arrange loans with lenders and put the financing together; a lender makes the loan. The CFPB draws the same line: a lender provides the money, a broker arranges the transaction.
What can a mortgage broker do that my bank can’t?
I have access to wholesale pricing, and I check the programs I can place against your income, property and loan needs. A loan officer working from one institution's menu has that menu to work with, and some institutions both lend and broker. My job is to check whether another available program fits your situation, and to say so plainly when none does. That does not mean I have access to every lender, or that every specialty program is available for every file.
My bank said no. Is there any point talking to you?
There can be. I start with the written reason for the denial, because a restriction at one lender is different from a problem that affects every available option. I can tell you what another lender would need to see and whether a second review is worth pursuing. If the reason is one that travels with the file, I will say that too.
Why would one lender count my income and another one wouldn’t?
Programs differ in the income they accept, the history they require and the documents they use. That matters when you own a business, receive stock or bonus compensation, live on investments or own rental property. I read those written requirements against your actual records before anything is submitted.
Do I need a non-QM loan just because I’m self-employed?
No. I check first whether a conventional, FHA, VA or other standard program can use your documented income, because those usually cost less. If none fits, I review the bank-statement, profit-and-loss, 1099 or asset-based options available through the lenders I work with and explain the differences.
Can you get an underwriter to make an exception?
I can present the documentation, explain the situation and ask whether the lender permits an exception. I cannot override its approval requirements, and no exception is promised. If that program does not fit, I check another lender I work with.
Does using a broker cost more, and how are you paid?
The CFPB explains that the person who arranges your mortgage is usually paid a loan-specific fee or commission, paid by you or by the lender you use, and that on most closed-end mortgages, federal law prohibits that pay from varying based on the loan’s terms. As a mortgage broker with West Capital Lending, I have access to wholesale pricing, and the lender pays my compensation on the back end; other loan and closing costs may apply. On the open market, my pricing is the best you’ll find.* If it isn’t better than going to that same lender directly, I won’t ask you to do the loan with me.
What clients say
Experience.com profile as observed on 2026-09-24, most recent review dated 2026-09-23. A dated observation, not a live feed.
I had a great experience working with my mortgage broker, Zach VonD. He was professional, knowledgeabele, and incredibly easy to work with throughout the entire process. He was always available to answer my questions, explained everything clearly and made the whole mortgage process feel smooth and stress free. I would definitely recommend him to anyone looking for a reliable and trustworthy mortgage professional.
"Zach is an exceptionally professional broker who stands out for his quick responses and strong customer orientation. He focuses on delivering immediate solutions to ensure an easy closing process for his clients. While WCL utilizes an automatic online processing system, Zach’s guidance makes navigating the platform completely seamless and difficulty-free. I highly recommend his service
Zach was so easy to work with. He made a stressful situation into a very positive experience for us and did push us one way or another. He listened to what we hoped we could accomplish and made it happen.
Zach VonD was great! He was very knowlegeable about different options and helped us choose what worked best for us! He was very efficient, he was very kind, courteous, very professional, and very eager to help us get what we wanted. When ever we asked questions he had the answers and if he needed to get back to us if we had any issues about anything he didn't waste any time at all. He was spot on about when our loan would close and when we would receive our funds! He was a joy to work with and I would call on him again for any of our mortgage needs! If he lived closer I would invite him over for a barbecue! I would recomend him to all my friends and family for their equity loan needs!
Selected excerpts. Read all reviews on Experience.com.
What clients consistently mention
- Responsive and easy to reach
- Explains the process clearly
- Patient guidance through decisions
- Finds options that fit the situation
Read the reviews on Experience.com
General service reviews; they do not prove a result for your situation or point to a particular lender.
The rating and count above were read from the Experience.com profile on 2026-09-24. The excerpts are word for word from that profile; none are edited or invented.
Licensing and identity
Every number below is public, and each is labeled with whose it is: Zach’s own NMLS and California DRE numbers first, then West Capital Lending’s company numbers. Enter either NMLS number at NMLS Consumer Access to see that record; the links are under the list.
- Zach, NMLS: 1652805
- Zach, California DRE: 02179302
- West Capital Lending, NMLS: 1566096
- West Capital Lending, California DRE: 02022356
- Experience: over 10 years and counting in mortgages
Review source: Experience.com profile, where he appears as Zach vonD. See also the disclosures page.
Sources and checked dates
Sources: Zach, September 10, 2026 (checked 2026-09-10) · Supplied by Zach, September 9, 2026 (checked 2026-09-09) · Experience.com profile (checked 2026-09-24) · Consumer Financial Protection Bureau, What is the difference between a mortgage lender and a mortgage broker? (checked 2026-10-17) · Consumer Financial Protection Bureau, How does a mortgage loan officer or broker get paid? (checked 2026-10-17) · 12 CFR 1026.36, Regulation Z, prohibited acts or practices and certain requirements for credit secured by a dwelling (CFPB) (checked 2026-10-18).
Show each claim on this page, what it depends on, and the date it was checked (8)
| What we say, and what it depends on | Source | Checked |
|---|---|---|
| Zach has been doing this for over 10 years and counting. | Zach, September 10, 2026 | 2026-09-10 |
| Zach says he has worked at banks and at direct lenders as an employee, and is now an independent broker who is not paid differently based on the type of loan product offered. | Zach, September 10, 2026 | 2026-09-10 |
| Zach says the number on this site is a direct line to his cell, that texts are welcome anytime, that he answers them himself when he is free, and that he takes calls during normal business hours. | Zach, September 10, 2026 | 2026-09-10 |
| Zach reports placing loans through more than one wholesale lender and program via his broker channel: the standard home equity line described on this site, plus conventional, government, bank statement and investment-property options. Individual lender names are kept off the public pages until the executed broker agreement for each is on file (California 10 CCR 2848(a)(3)). | Supplied by Zach, September 9, 2026 | 2026-09-09 |
| The Experience.com profile for “Zach vonD,” West Capital Lending, displayed a 5.0 overall rating and 66 reviews, with 10 entries visible per page, when fetched live on September 24, 2026 (UTC); the page header, pagination and embedded structured data agreed, and the newest review was dated September 23, 2026. Earlier fetches: September 10, 2026 showed 63 reviews; a cached snapshot retrieved September 9, 2026 showed 52 and was marked as crawled about three months before. | Experience.com profile | 2026-09-24 |
| The CFPB's Ask CFPB page "What is the difference between a mortgage lender and a mortgage broker?" (last reviewed December 11, 2024): "A lender is a financial institution that makes direct loans. A broker does not lend money. You can use a broker to find different lenders or mortgage loans." "When you take out a loan with a lender, you pay them back based on the terms of your loan. When you work with a broker, you pay them a loan-specific fee for their services." "Some financial institutions operate as both lenders and brokers, so you should ask whether a broker is involved in your loan transaction." | Consumer Financial Protection Bureau, What is the difference between a mortgage lender and a mortgage broker? | 2026-10-17 |
| The CFPB's Ask CFPB page "How does a mortgage loan officer or broker get paid?" (last reviewed January 7, 2025): "When you work with someone to get a mortgage, they are usually paid a loan-specific fee or commission. This money is paid by you or by the lender you use." "Mortgage loan officers often work for one specific lender. Mortgage brokers typically work with multiple lenders." "While federal law prohibits commissions from varying based on the terms of the mortgage, lenders can pay mortgage loan officers and brokers in many ways." "Before you work with a loan officer or broker, make sure you understand their fees and who pays them." | Consumer Financial Protection Bureau, How does a mortgage loan officer or broker get paid? | 2026-10-17 |
| Regulation Z, 12 CFR 1026.36, as published on the CFPB's regulations site. Its scope paragraph, 1026.36(b): "Paragraphs (d) through (i) of this section apply to closed-end consumer credit transactions secured by a dwelling. This section does not apply to a home equity line of credit subject to § 1026.40," except for two paragraphs that do not concern pay. Its 1026.36(d)(1)(i): "in connection with a consumer credit transaction secured by a dwelling, no loan originator shall receive and no person shall pay to a loan originator, directly or indirectly, compensation in an amount that is based on a term of a transaction." | 12 CFR 1026.36, Regulation Z, prohibited acts or practices and certain requirements for credit secured by a dwelling (CFPB) | 2026-10-18 |
Written for and accountable to: Zach von der Linden, Mortgage broker and Branch Manager, West Capital Lending.
Last updated 2026-10-17.
Verify him: NMLS Consumer Access, ID 1652805 · 66 reviews on Experience.com.
Sources for product claims are listed on this page, with the date each was checked.
*Special situations can be the exception, such as relationship pricing from a bank or wealth firm where you hold significant assets, or from a credit union you have a long relationship with. If that’s you, I’ll tell you when that offer makes more sense.
No credit pull happens from a conversation. Texts go to Zach's cell.